Finance Brokers in Brisbane, QLD
Finance for every stage of your Brisbane journey.
From your first home to your growing business, our Brisbane team structures finance around your goals and your timeline.
Brisbane Head Office
Brisbane is home base for Finstac, and where our team works closely with the local market.
Finstac is based in Brisbane, working with clients across the city and the wider South East Queensland region. Our team takes the time to understand your situation before recommending a lender or a structure, so the finance fits the goal rather than the other way around.
Whether you are purchasing a first home, refinancing, growing a business, or building an investment portfolio, our Brisbane office is the place to start that conversation.
A clear process and the right lender to match, so you understand every step before you commit to it.
Visit us
Our Brisbane office.
- Address
- 35 Dover Street
Albion QLD 4010 - Phone
- 0475 024 328
- 01Former commercial bankers
- 02Access to 100+ lenders
- 03A director on every file
- 04A reply within one business day
Suburbs we work across
Albion, Hamilton, Ascot, New Farm, Newstead, Clayfield, Chermside, Kedron, Aspley, Paddington, Bulimba, Camp Hill, Coorparoo, Indooroopilly, Teneriffe, Bardon, Red Hill, St Lucia, Toowong, Hawthorne, Wilston, Ashgrove, Fig Tree Pocket, and the wider Brisbane region.
Local knowledge
What we see in the Brisbane market.
Inner north and river suburbs
Ascot, Hamilton and Clayfield transactions frequently involve larger loan sizes and more complex income: practice owners, specialists and executives. Lender selection matters more here than headline rate, because policy on bonus, trust and practice income varies widely.
Northside first home buyers
Chermside, Kedron and Aspley remain among the most common first-purchase corridors we see. The deciding factor is usually deposit structure and scheme eligibility rather than borrowing capacity alone.
Renovation and upgrade lending
A lot of Brisbane stock is pre-war and character-protected. Renovation lending, construction facilities and valuation treatment of unrenovated homes come up constantly, and lenders differ significantly in how they handle them.
Small business and trades
Brisbane's trade and services sector drives steady demand for equipment and working capital finance, often alongside a home loan for the same client. We look at both together.
General observations from our own client work. Not market forecasts, property advice or a prediction of future values.
Lender access
Access to 100+ banks and specialist lenders, including:
Plus many more specialist and private lenders
Where we are
Common questions
Brisbane home loan and finance questions.
No. Most Brisbane clients do everything by phone, email and video, and we'll come to you if a face-to-face suits better. The office is at 35 Dover Street, Albion if you'd prefer to meet there.
All of them, plus the wider South-East Queensland region. Our head office is in Albion and most of our client base sits across greater Brisbane, Ipswich, Logan and Redlands.
Yes. Queensland has its own transfer duty scale plus a home concession and a first home concession, with thresholds that differ from other states. Our stamp duty calculator applies the Queensland rules.
We'll check which state and federal schemes you qualify for as part of the first conversation. Eligibility rules change regularly, so we confirm current criteria rather than working from last year's.
Yes. Loans above about $2 million are assessed differently. Many lenders lower the maximum LVR at that level, ask for more detail on income and assets, and order a full valuation rather than a desktop one. We work out which lenders suit the loan size and the property before anything is submitted, so the valuation and the credit decision line up.
Regularly. Some lenders offer eligible professionals a higher LVR with Lenders Mortgage Insurance reduced or waived, and some read practice, partnership and trust income more favourably than others. Eligibility depends on your profession, registration and the lender's current policy, which we confirm before recommending anything.
Often, yes. Bridging finance lets you settle the new purchase while your current home is on the market. Lenders look at the peak debt and the end debt, and their terms vary a lot. We map both, including what happens if the sale takes longer than planned, before you sign a contract.
They can. Character overlays, renovation needs and unusual floor plans affect how valuers assess a home. We choose lenders whose valuation approach suits character properties and set expectations on value early, so there are no surprises after you have signed.
Our people
The people behind Finstac Brisbane.
A small senior team, by design. You deal directly with the people who built the business, from the first conversation through to settlement.
Meet our people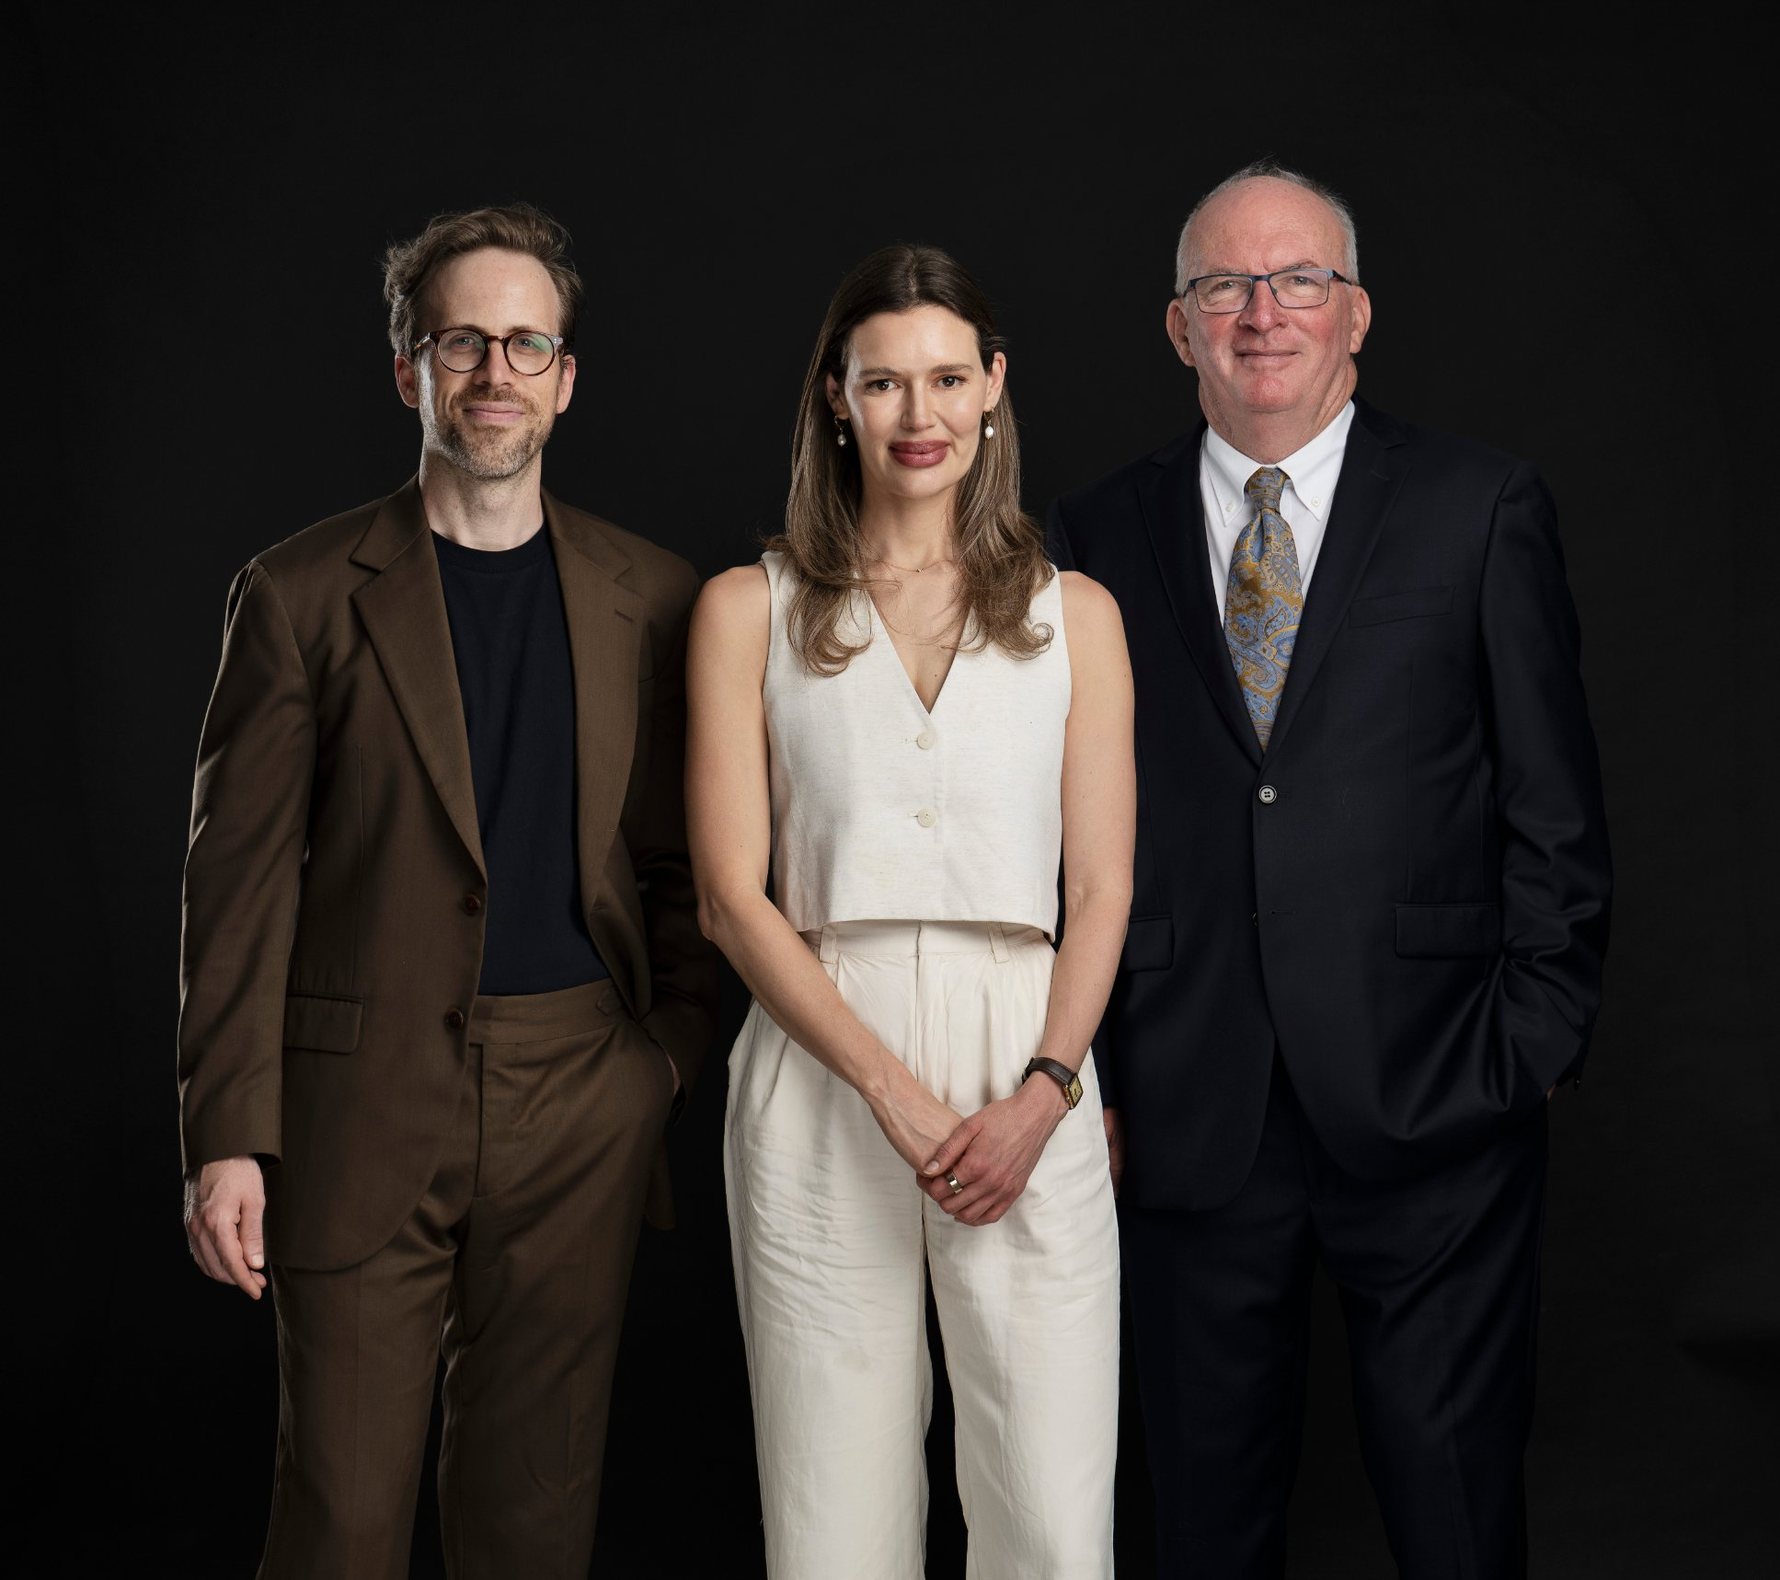
The process
How it works.
Tell us what you're trying to do
A quick conversation gives us the context: your goal, your timeline and where you're up to.
We assess your position
We look at your circumstances, objectives and the lending options actually available to you across the lenders we have access to.
We structure the strategy
We identify an appropriate lending approach, and explain the trade-offs in plain English before you commit.
We handle the process
From application through to settlement, we stay involved and keep you updated.
Talk to someone about Brisbane finance.
Three quick questions, then a director comes back to you within one business day. No obligation, and we'll tell you honestly if the answer is “not yet”.