Finance Brokers on the Sunshine Coast, QLD
Finance for one of Australia's fastest growing regions.
From new estates to established character homes, our Sunshine Coast team helps you move forward with confidence.
Sunshine Coast
A region growing quickly, and finance support that keeps pace with it.
The Sunshine Coast has experienced significant growth in recent years, and our local team works with residents, new arrivals, and business owners navigating that change. We focus on clear communication and a process you can follow at every step.
From new build finance to refinancing and business lending, our Sunshine Coast office is here to support your next move.
Growth creates opportunity. A clear finance process helps you make the most of it.
Visit us
Our Sunshine Coast office.
- Address
- 36a Browning Blvd
Battery Hill QLD 4551 - Phone
- 0475 024 328
- 01Former commercial bankers
- 02Access to 100+ lenders
- 03A director on every file
- 04A reply within one business day
Suburbs we work across
Maroochydore, Mooloolaba, Buderim, Caloundra, Noosa Heads, Coolum Beach, Battery Hill, Sippy Downs, Nambour, Peregian, Kawana, Currimundi, Sunshine Beach, Sunrise Beach, Noosaville, Tewantin, Twin Waters, Minyama, Mount Coolum, and the wider Sunshine Coast region.
Local knowledge
What we see in the Sunshine Coast market.
New builds and house-and-land
A large share of Sunshine Coast activity is new construction. Construction lending runs on progress payments and has its own approval and valuation process. It is not the same as buying an established home.
Relocating buyers
Many buyers are moving up from Brisbane or interstate, sometimes before securing local employment. How a lender treats that transition varies, and it's usually solvable with the right lender.
Acreage and lifestyle blocks
Hinterland and acreage properties face land-size limits, zoning treatment and valuation approaches that differ by lender. Confirming this before contract avoids a lot of pain.
Self-employed and seasonal income
The local economy skews toward small business, trades, tourism and health. Seasonal and self-employed income needs to be presented properly to be assessed properly.
General observations from our own client work. Not market forecasts, property advice or a prediction of future values.
Lender access
Access to 100+ banks and specialist lenders, including:
Plus many more specialist and private lenders
Where we are
Common questions
Sunshine Coast home loan and finance questions.
36a Browning Blvd, Battery Hill. Most of the process runs by phone, email and video, with a director on your file throughout.
Yes. Construction lending draws down in stages against progress payments, and the approval, valuation and cashflow work differently to a standard purchase. It's worth understanding the sequence before you sign a build contract.
Usually, though land size, zoning and access affect which lenders will lend and at what LVR. Larger blocks can narrow the choice of lenders considerably.
Not inherently. It's a presentation and lender-selection question. Our self-employed income calculator gives you a sense of how add-backs may affect your assessable income.
Yes. Prestige coastal purchases usually involve lower LVR limits at higher loan sizes and a full valuation. We place the loan with lenders comfortable with the loan size and the property, and prepare the file so the valuation supports the price.
Possibly. Some lenders count short stay income with a proven track record, others discount it heavily or exclude it. If letting is part of your plan, we choose a lender whose policy suits how the property will actually be used.
It can. Lenders want to see that your role and income continue after the move. A letter from your employer confirming remote work usually settles it, and we prepare the application so the change of location raises no questions.
Often. Many lenders limit standard residential lending to a certain land size, and larger or income producing rural blocks may need a specialist lender. We check the land size, zoning and use first, then choose a lender that fits.
Our people
The people behind Finstac Sunshine Coast.
A small senior team, by design. You deal directly with the people who built the business, from the first conversation through to settlement.
Meet our people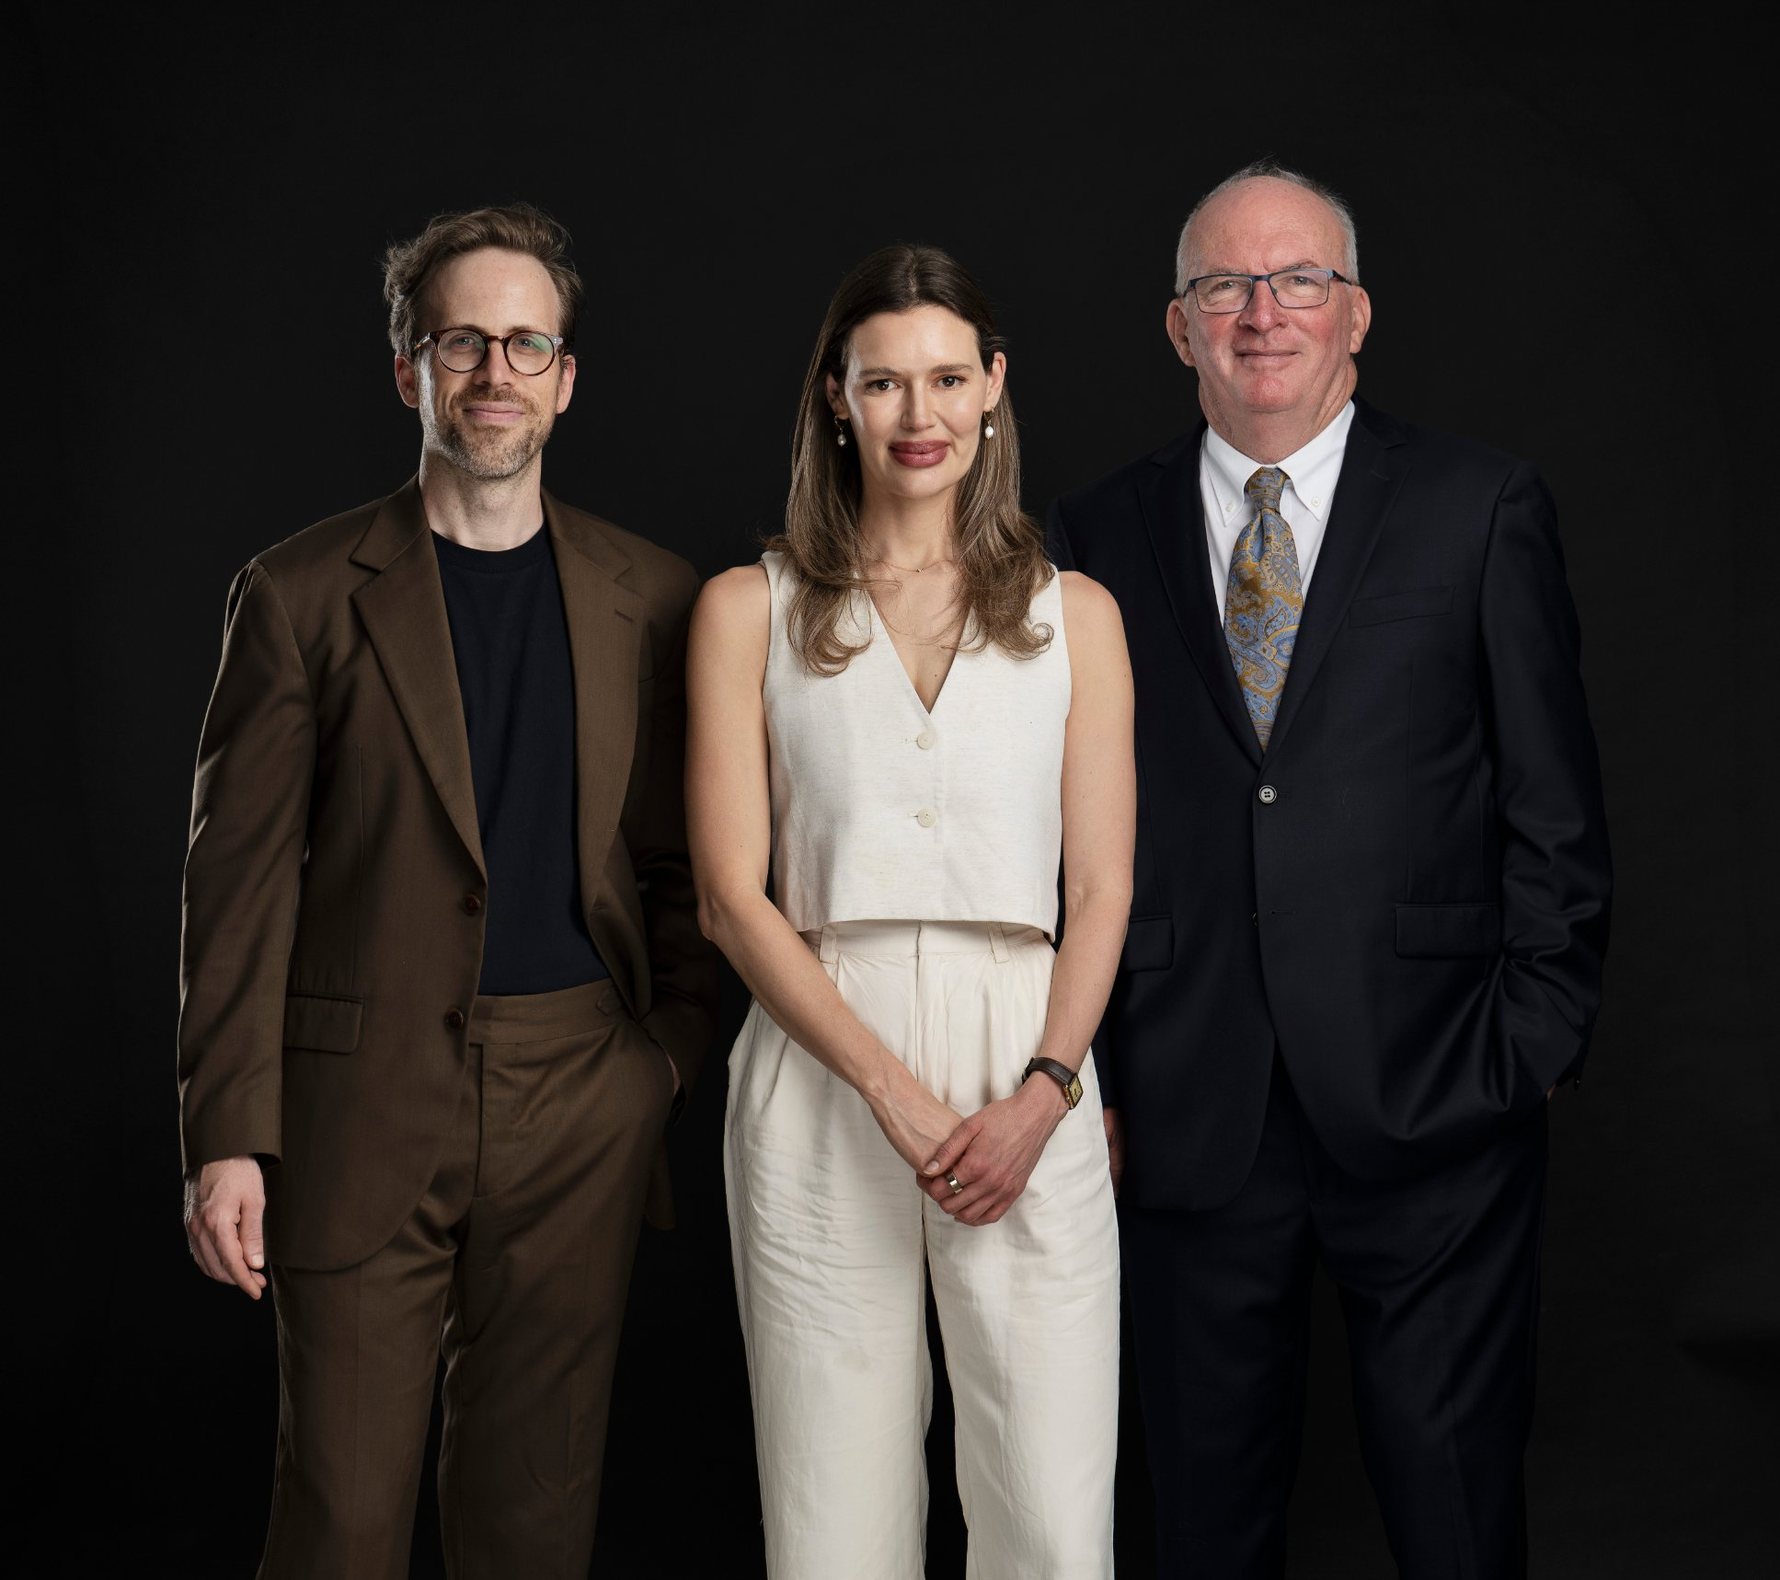
The process
How it works.
Tell us what you're trying to do
A quick conversation gives us the context: your goal, your timeline and where you're up to.
We assess your position
We look at your circumstances, objectives and the lending options actually available to you across the lenders we have access to.
We structure the strategy
We identify an appropriate lending approach, and explain the trade-offs in plain English before you commit.
We handle the process
From application through to settlement, we stay involved and keep you updated.
Talk to someone about Sunshine Coast finance.
Three quick questions, then a director comes back to you within one business day. No obligation, and we'll tell you honestly if the answer is “not yet”.