Property Investors
Your equity is doing nothing.
Most investors hit a wall not because they've run out of equity, but because their lending was structured without the next purchase in mind. That's fixable, usually before you need it to be.
- Usable equity mapped properly, not guessed from an online estimate
- Cross-collateralisation untangled
- Structured so your borrowing capacity survives the next purchase
- We coordinate with your existing accountant
Get started
Tell us what you're trying to do.
Who you'll be dealing with
Jonathon Radford, Director
- Master of Applied Finance, majoring in Investment Management
- Advanced Diploma of Financial Planning
- Diploma of Finance and Mortgage Broking Management
- 15+ years across commercial banking, investments and wealth management
- 15+ years of business ownership and operating experience
Finstac Pty Ltd, Credit Representative 582083, authorised under Elders Home Loans Pty Ltd, Australian Credit Licence 384408
The situation
Why your bank keeps saying no.
One lender holding every property means one lender's appetite decides your entire portfolio. When they say no, or revalue conservatively, you're stuck, and untangling it later is expensive.
Serviceability ceilings do the rest. Two investors with identical incomes and identical equity can have wildly different borrowing capacity depending purely on how their existing loans were structured and which lender assesses them.
We look at the portfolio, not the deal in front of you. Where the structure is limiting you, we'll say so, and map what changing it would actually free up.
Why Finstac
How we work with investors.
Usable equity, honestly
What a lender will actually release, at what LVR, and what that supports. Not the number a property website tells you.
Structure that keeps you buying
Splitting lending across lenders where it protects your options, and avoiding cross-collateralisation that costs you flexibility later.
Lender policy knowledge
Investment policy varies enormously between lenders: rental income treatment, existing debt assessment, interest-only appetite. We know which lenders suit which strategies.
Coordinated with your accountant
Structure and tax questions sit between broker and accountant. We work alongside yours rather than around them.
Want the real number, not an estimate?
A director will run your actual position across the 100+ lenders we have access to.
The process
How it works.
Tell us what you're trying to do
A quick conversation gives us the context: your goal, your timeline and where you're up to.
We assess your position
We look at your circumstances, objectives and the lending options actually available to you across the lenders we have access to.
We structure the strategy
We identify an appropriate lending approach, and explain the trade-offs in plain English before you commit.
We handle the process
From application through to settlement, we stay involved and keep you updated.
Free guide
The Investor's Loan Structure Guide
Equity, structure and borrowing capacity
- How to work out your usable equity
- Cross collateralisation explained, and why it limits your options
- Structuring loans so your borrowing capacity survives the next purchase, and what the 2027 tax changes mean
- The investment loan features that actually matter
Straight answers
The questions we get asked most.
The things people actually ask before they pick up the phone. If yours isn't here, ask us directly and we'll give you a straight answer either way.
That's exactly the constraint. One lender's policy currently determines what your whole portfolio can do. Spreading lending doesn't mean leaving them. It means they no longer hold a veto.
Understood, and we won't push you to. Knowing your usable equity doesn't commit you to using it, but not knowing it means you can't act when something worth acting on appears.
Fair. Ask any broker to explain how your loans are currently cross-collateralised and what untangling them would cost. The answer tells you quickly whether they're looking at your portfolio or just this deal.
Complex portfolios are the ones where structure matters most. A director reads the whole file. That's the point of us.
No. We're finance brokers, not investment advisers, and we don't make projections about property returns. We structure the lending. The investment decision stays yours and your advisers'.
Most count 70–80% of it, to allow for vacancy and holding costs. Some are more generous with certain property types. That shading is often the difference between an approval and a decline.
Usually yes. Releasing equity from an existing property is one of the most common ways investors fund the next purchase. You still need to service the additional borrowing.
There's no fixed number. It's determined by serviceability and structure, which is why two investors with similar incomes can end up in very different positions.
One lender holding two or more of your properties as security for your loans. It's convenient at the time and restrictive later, because selling or refinancing one property drags the others into the decision.
That's a tax and asset-protection question for your accountant, not us. Once you've decided, we structure the lending around it, and we'll flag where a structure will limit your borrowing options.
Investor · Case study
Investor stuck at three properties, with equity going nowhere.
The situation
An investor with three properties, all held with a single lender and cross-collateralised. Substantial equity on paper, and a bank that had declined the next purchase twice.
The problem
Every property secured every loan. One lender's serviceability model and one valuer's opinion governed the entire portfolio, and releasing equity meant revaluing everything, which had already gone against them once.
What we did
- Mapped total equity against genuinely usable equity at 80% LVR
- Untangled the cross-collateralisation as part of a refinance rather than as a standalone exercise
- Split the portfolio across two lenders so no single lender held a veto
- Structured the release so the next purchase didn't require re-approval of existing debt
The outcome
Usable equity was released to fund the next deposit, and borrowing capacity was restored by moving part of the portfolio to a lender with a more favourable rental income treatment.
The numbers
- Portfolio value
- $2.4m
- Total lending
- $1.42m
- Usable equity released
- $285,000
- Lenders after restructure
- 2 (from 1)
- Next purchase funded
- Within 90 days
Illustrative example based on typical client scenarios. Individual circumstances, lender policies and outcomes vary. Not a guarantee of approval or result.
More like thisLender access
Access to 100+ banks and specialist lenders, including:
Plus many more specialist and private lenders
Our people
The people behind Finstac.
A small senior team, by design. You deal directly with the people who built the business, from the first conversation through to settlement.
Meet our people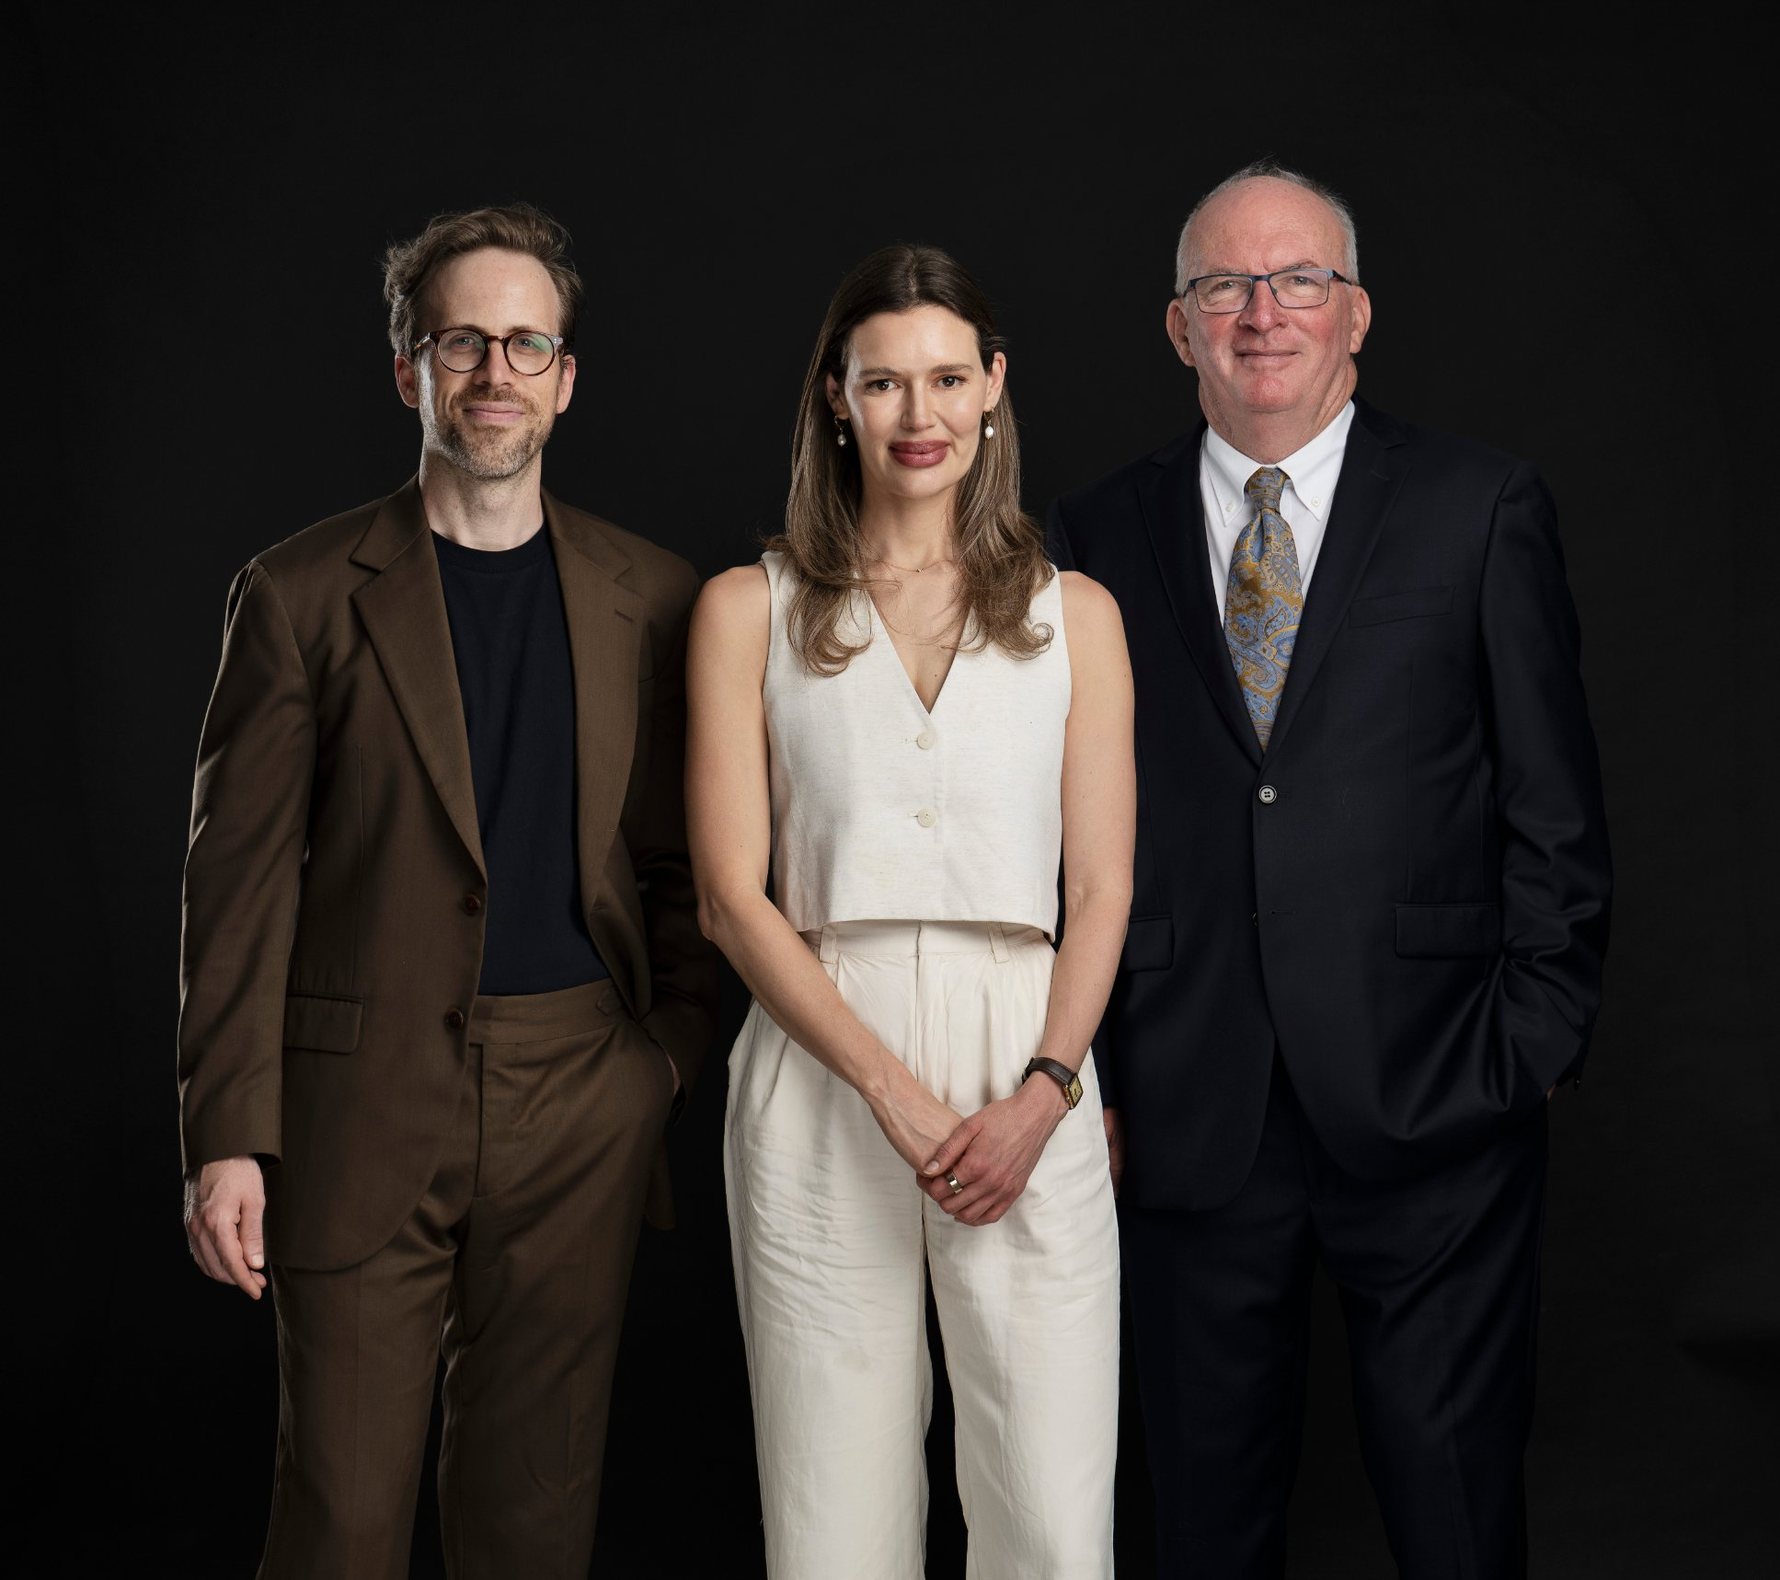
Ready when you are.
Three quick questions, then a director comes back to you within one business day. No obligation, and we'll tell you honestly if the answer is “not yet”.